472,000 EVs, 46,000 Charging Connectors in Türkiye: Is Infrastructure Keeping Up?
In August 2026, Türkiye had 46,665 charging connectors for 472,157 electric cars. We compared the growth rates of cars and connectors side by side, along with the ratio, the DC share, and the tariff gap.
472,157: that was the number of registered electric cars on Türkiye's roads at the end of August, according to TÜİK (Türkiye's statistical institute) data. A year earlier, in August 2025, the figure was 308,217 — a year-on-year increase of 53.2 percent. The gap is 163,940 cars, which is exactly how many new electric cars hit the road in twelve months.
The curve isn't new, but it is steep. According to TÜİK's series, Türkiye had 183,776 electric cars at the end of 2024, and that number climbed to 370,591 by the end of 2025. In other words, the car count roughly doubled last year, and it's still growing by about half this year. The question that needs asking is simple: is the number of charging connectors growing at the same rate?
The car count rose by 164,000 in twelve months — connectors didn't keep pace
According to EPDK's (Türkiye's energy market regulator) own electric vehicle data, Türkiye had 464,873 cars at the end of July 2026, up from 450,038 at the end of June. The same report puts the total number of commercially operated charge points at 46,665 — 26,204 of them AC, 20,461 DC.
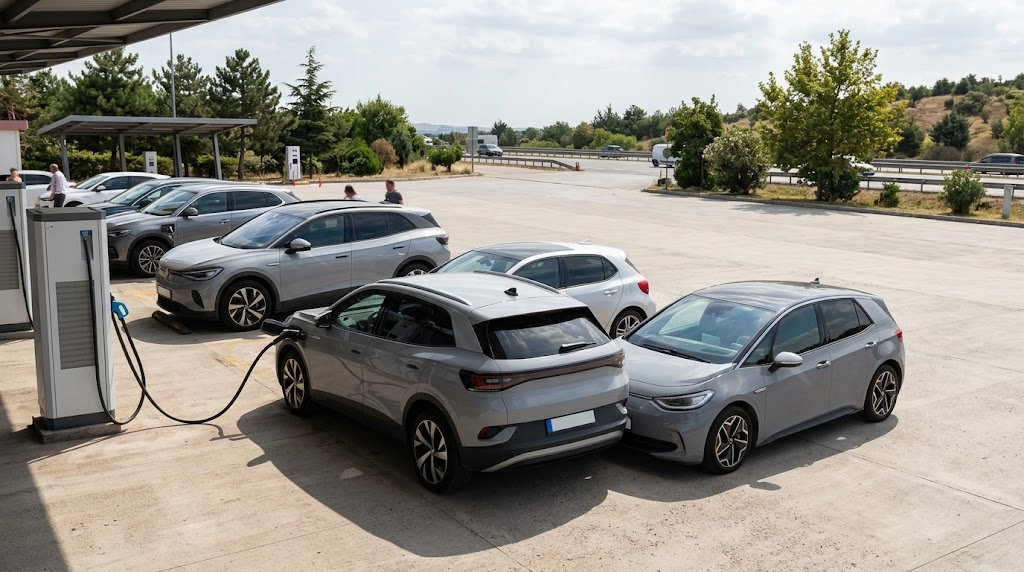
Divide those two numbers and the ratio is clear: 464,873 divided by 46,665 is roughly 10. In Türkiye, there's one charging connector for every 10 electric cars. A year earlier, in July 2025, the picture was a bit different: total connectors stood at 32,682 (18,888 AC, 13,794 DC), while the car count was just over 291,000. Back then the ratio was roughly 1 connector for every 9 cars. The ratio got worse over the year, not better.
Lining up the growth rates gives the same answer. Connectors grew 42.8 percent in a year (from 32,682 to 46,665); cars grew 59.8 percent over the same period (from 291,000 to 464,873). The car side is running seventeen points faster than the connector side. Infrastructure isn't keeping up in sheer numbers — the gap is widening.
Connectors aren't standing still either, but the ratio still tilts against cars
Looking one month ahead, at August 2026, there's movement on the connector side too: according to the EPDK Energy Transformation Department's report, the total number of connectors rose to 47,908 — 27,044 AC, 20,864 DC. That's 1,243 new connectors added in a single month. Annualized, that's roughly 15,000 connectors a year — even at that pace, it stays far below the 164,000 annual increase on the car side.
Let's not overstate this: 46,000 connectors isn't a small number — it's a network built from scratch. But the question isn't "is it growing," it's "is it growing as fast as the car count." Based on the numbers we have, the answer to the second question is no.
The DC share has barely changed
While the total connector count keeps rising, the AC-DC split has stayed surprisingly stable. In July 2025, 42.2 percent of connectors were DC; that share rose to 43.8 percent in July 2026 and sat at 43.5 percent in August 2026. In other words, while the connector count grew by nearly double, the DC share moved by only a point and a half.
For drivers, that means: out of every 10 connectors out there, 4 are fast charging and 6 are AC. What's more, of the 1,243 connectors added last month, only 403 were DC — a third of the new capacity. Leave your car at an AC charge point and you're waiting hours; since the composition stays the same even as the count grows, on-the-road fast-charging capacity is opening up more slowly than the total connector count suggests.
What you pay for the same kWh can nearly double depending on the operator
It's worth looking at this picture from the price side too. According to Voltbu's current tariff data, compiled from 173 operators as of October 7, 2026, the operator median for AC charging is 9.90 TL/kWh, but the range runs from 5.90 to 13.99 TL. On the DC side, the median is 12.99 TL/kWh, ranging from 7.70 to 16.49 TL. The median for fast DC tiers of 150 kW and above sits around 12.99 TL as well — meaning there's practically no extra price gap left for higher-power charging.
Here's what that looks like with an actual fill-up: charge a 60 kWh battery on AC at the cheapest operator and you pay 354 TL; at the most expensive, 839 TL — a 2.37x difference. Do the same fill-up on DC and it's 462 TL at the cheapest, 989 TL at the most expensive — a 2.14x difference. You're getting the same energy, but the bill nearly doubles depending on which operator you happen to use.
Two numbers worth keeping in mind: density and the tariff range
First, it's true that the number of connectors along your route has grown over the past year, but it's also true that it hasn't grown as fast as the car count — which is why it makes sense to factor in waiting for your turn on long trips, and to line up a backup spot, especially during busy hours. Second, know that the tariff median doesn't sit in the middle of the range: you're choosing an operator somewhere between 5.90 and 13.99 on AC, or between 7.70 and 16.49 on DC; checking that charge point's price as well as its location when planning your route can mean a difference of close to 100 percent for the same fill-up.
If you want to work out your own number, the formula is simple: multiply your battery's kWh capacity by the TL/kWh price of the operator you're heading to. The difference can add up to hundreds of lira over a full fill-up — treating this as a variable when you plan your route means looking not just for the "nearest connector," but the "nearest reasonably priced connector."
Sources
Mert Ali Karausta
Writes about mobility technology and the electric vehicle ecosystem. Works actively on the Voltbu team.
Comments
You need to sign in to comment.
Sign InNo comments yet. Be the first to write one.